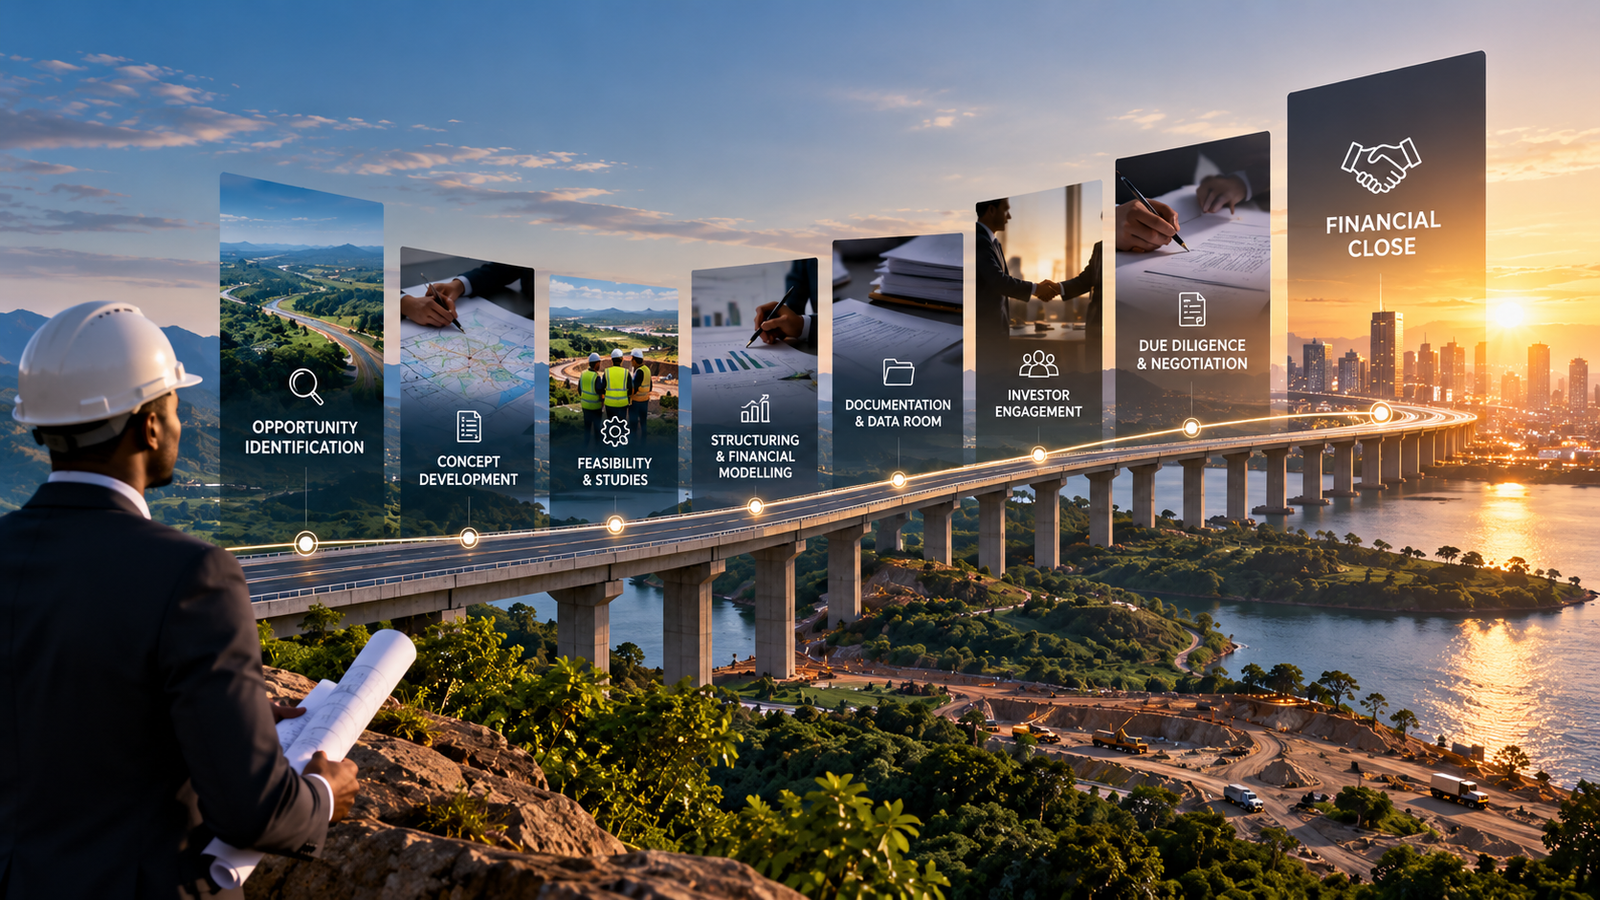
Most projects do not fail because the underlying idea is weak. They stall in the distance between being identified as an opportunity and becoming a transaction that capital providers are prepared to finance.
Across infrastructure and other capital-intensive sectors, project pipelines can appear substantial. Governments, developers and businesses may identify many opportunities with genuine economic potential.
Yet comparatively few projects progress smoothly from concept to signed financing.
The difficult part is often not identifying the opportunity.
It is transforming that opportunity into a transaction that can withstand financial, commercial, technical and legal scrutiny — and then managing the financing process until close.
That gap between pipeline and financial close is where disciplined preparation, structuring and transaction execution become critical. Aderra_Website_Copy_Script
A pipeline is not the same as an investable project
A project can appear on a development pipeline long before it is ready for capital.
At that stage, important questions may still be unresolved:
- Is the revenue model sufficiently clear?
- Has the project been properly costed?
- Are the key commercial agreements in place?
- Is risk allocated appropriately?
- Does the financial model reflect the realities of the project?
- Is the proposed capital structure sustainable?
- Is the documentation ready for due diligence?
These questions determine whether a project is simply an opportunity or a credible financing proposition.
The transition between the two requires work.
Where transactions lose momentum
Financing processes often slow down when unresolved issues surface after investors or lenders have already been approached.
EnfraCo’s original perspective identifies several recurring causes:
Unresolved risk allocation
If construction, operating, counterparty, regulatory or other key risks have not been clearly addressed, capital providers may struggle to evaluate the transaction.
Financial models that cannot answer lender questions
A model should do more than present attractive projections. It needs to show how the project behaves under different assumptions and whether the proposed financing can be supported.
Incomplete documentation
Missing commercial, financial or legal information can delay due diligence and weaken confidence in the transaction.
Approaching the wrong forms of capital
Not every lender or investor is appropriate for every project. Poorly targeted outreach can consume time without moving the financing process forward. Aderra_Website_Copy_Script
Each of these problems can reduce momentum.
More importantly, many can be addressed before formal fundraising begins.
Preparation creates momentum
A financing process becomes easier to manage when the project enters the market with the fundamental work already completed.
That means sponsors should understand:
- How much capital is required
- What the capital will finance
- What type of financing is appropriate
- How much debt the project can realistically support
- What risks investors will focus on
- Which documents will be required
- Which capital providers are most relevant
The goal is not to eliminate every possible question.
It is to ensure that the transaction is sufficiently prepared to answer the questions that matter.
Preparation allows financing discussions to focus on the substance of the opportunity rather than basic gaps in the transaction.
The financial model must remain connected to the transaction
The financial model is not a document that is completed once and then left unchanged.
As a transaction progresses, assumptions evolve.
Construction costs may change.
Financing terms may be proposed.
Timelines may shift.
Commercial agreements may be revised.
The financial model needs to remain current so that sponsors and capital providers can understand the impact of those changes.
A financing decision made using an outdated model can create a disconnect between the transaction being negotiated and the economics the project can actually support.
Maintaining that connection is an important part of transaction execution.
The data room matters
Due diligence is one of the most important stages between investor interest and financial close.
Capital providers need access to the information required to assess the opportunity.
That can include:
- Financial information
- Commercial agreements
- Project documentation
- Technical studies
- Legal documents
- Corporate information
- Regulatory materials
- Financing assumptions
A well-managed data room helps ensure that information is organized, current and accessible.
It also reduces unnecessary delays caused by repeated requests for documents that should already be available.
EnfraCo’s original transaction perspective specifically highlights keeping both the model and data room current as part of managing a transaction toward close. Aderra_Website_Copy_Script
A term sheet is not the finish line
Receiving a financing proposal can feel like a major milestone.
It is.
But a term sheet still needs to be evaluated against the actual economics of the project.
The lowest headline interest rate, highest leverage or largest financing commitment is not automatically the best structure.
Sponsors need to consider the entire financing package, including:
- Repayment profile
- Tenor
- Security requirements
- Covenants
- Conditions precedent
- Pricing
- Reserve requirements
- Restrictions on distributions
- Sponsor obligations
The central question remains:
Can the project realistically carry the financing being proposed?
A transaction should be structured around the capacity of the underlying project rather than around the maximum amount of capital available.
Negotiation requires discipline
Financing negotiations can involve multiple parties with different priorities.
Sponsors want sufficient capital and manageable terms.
Lenders want adequate protection and confidence in repayment.
Equity investors may focus on returns, governance and exit options.
Technical, legal and other advisors may identify issues that affect the structure.
Transaction execution requires these workstreams to remain coordinated.
Decisions made in one area can have consequences elsewhere.
For example, changes to a commercial agreement may affect the financial model, which may then affect debt capacity and ultimately change the financing terms.
Managing those dependencies is part of moving the transaction forward.
Keep the process moving
Financial close is not simply the result of finding an interested capital provider.
It is the result of managing a process.
EnfraCo’s original perspective describes this as sequencing diligence, keeping the financial model and data room current, evaluating term sheets against the project’s real capacity and keeping counterparties working toward a timeline. Aderra_Website_Copy_Script
That requires clear ownership of:
Information
What has been requested, what has been provided and what remains outstanding?
Decisions
Which commercial and financing issues still require resolution?
Responsibilities
Who is accountable for each workstream?
Timelines
What needs to happen before the next stage of the transaction can proceed?
When these elements are not actively managed, even strong transactions can lose momentum.
Financial close is built through a sequence of decisions
It can be tempting to view financial close as a single event.
In reality, it is the outcome of many earlier decisions.
The project has to be prepared.
The financing strategy has to be appropriate.
The right capital providers need to be engaged.
Due diligence needs to be completed.
Financing terms need to be evaluated.
Outstanding issues need to be resolved.
Documentation needs to be finalized.
Each stage builds on the one before it.
A weakness early in the process often reappears later as a delay, negotiation issue or financing constraint.
The Advisor’s Role
The role of a transaction advisor is not simply to introduce a project to investors.
It is to help maintain the credibility and momentum of the financing process.
That may involve:
- Testing financeability
- Strengthening financial analysis
- Developing the capital strategy
- Preparing investment materials
- Coordinating investor or lender engagement
- Reviewing financing proposals
- Supporting due diligence
- Managing transaction workstreams
- Supporting negotiations toward financial close
The objective is to keep the transaction moving without overstating what any individual step can guarantee. Aderra_Website_Copy_Script
From Pipeline To Transaction
Strong project pipelines matter.
But ultimately, infrastructure and productive investment are financed through transactions — not pipeline numbers.
Moving from one to the other requires more than an attractive project concept.
It requires:
Preparation
A project sufficiently developed for institutional scrutiny.
Structure
A financing approach aligned with the economics and risk profile of the opportunity.
Capital strategy
A clear understanding of the forms of capital that are appropriate.
Execution
Disciplined management of diligence, negotiations, documentation and timelines.
The difference between a promising pipeline opportunity and a successfully financed project is often the quality of the work that happens between those two points.
EnfraCo Perspective
At EnfraCo Capital Partners, we support sponsors across the financing lifecycle — from assessing financeability and developing financial structures to capital raising and transaction execution.
Our role is to help turn credible opportunities into financing propositions that can progress through institutional scrutiny and toward financial close.
Prepare well. Structure appropriately. Execute with discipline.
Discuss a Project →